Summary
- Independent lawmaker Han Dong-hoon said the planned virtual asset (cryptocurrency) tax due to take effect in 2027 should be postponed again.
- Han said assets can be moved to overseas exchanges or private wallets, creating tax equity issues with users of domestic exchanges, and added that CARF alone would make it difficult to secure sufficient transaction records.
- He said some investors may move to overseas exchanges or private wallets once taxation begins on annual virtual asset income above 2.5 million won ($1,860), adding, “As I did in 2024, I will step in and stop it again this time.”
Forecast Trend Report by Period

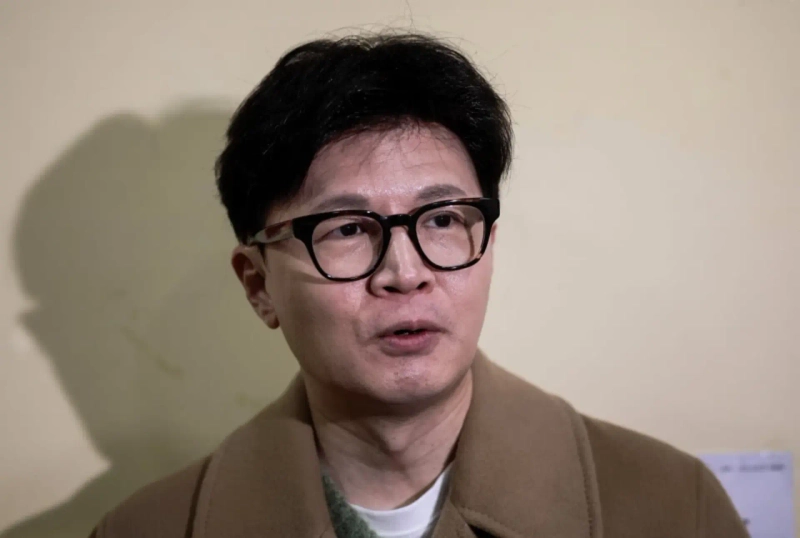
Independent lawmaker Han Dong-hoon said South Korea should again delay a planned tax on virtual assets, or cryptocurrencies, that is due to take effect in 2027.
News1 reported on September 15 that Han, in a Facebook post, said the government was still unprepared to impose the tax. “A lot has happened over the past two years, but I have no choice but to again point out that preparations for taxation are still not in place,” he wrote, calling for another postponement.
Han argued that virtual assets can be transferred to overseas exchanges or private wallets, creating tax equity issues with users of domestic exchanges. He also cited limits to relying on overseas financial account reporting and the Crypto-Asset Reporting Framework, or CARF, saying those measures alone would make it difficult to fully obtain transaction records.
He added that some investors could move to overseas exchanges or private wallets once taxation begins on annual virtual-asset income exceeding 2.5 million won ($1,860).
Han also referred to a National Assembly public consent petition this year seeking a delay in crypto taxation that drew support from more than 50,000 people. “As I did in 2024, I will step in and stop it again this time,” he wrote.

Minseung Kang
minriver@bloomingbit.ioBlockchain journalist | Writer of Trade Now & Altcoin Now, must-read content for investors.