Yoo Dong-won Says AI Cycle Isn’t Over Yet, Sees Appeal in US Growth Stocks
Summary
- Yoo Dong-won said the argument for moderating the pace of AI investment could help prevent overinvestment and extend the investment cycle.
- He said the recent correction has created a chance to revisit US growth stocks and the Nasdaq, given valuations and investor sentiment.
- He identified optical communications as a promising sector and said optical technology has ample room to grow.
Forecast Trend Report by Period

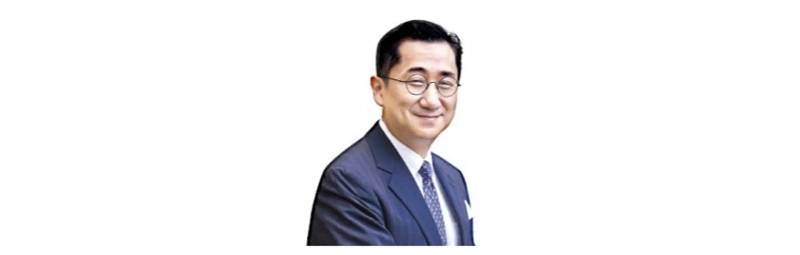
Yoo Dong-won, head of global asset allocation at Yuanta Securities
Moderating AI investment can prevent overinvestment
Bull-market potential after the US midterm elections
“It is wrong to interpret calls to moderate the pace of artificial intelligence investment as signaling the end of the cycle. If anything, that could improve the quality of investment and help extend the cycle.”
Yoo Dong-won, head of global asset allocation at Yuanta Securities, made the remarks in a recent interview with the Korea Economic Daily. He said a more measured pace of AI investment could curb excessive capital spending and ultimately lengthen the investment cycle.
He contrasted the current environment with the dot-com bubble, when overinvestment sharply eroded margins and reduced profits. This time, he said, rising revenue is being backed by profitability. Yoo is an investment strategist with 33 years of experience analyzing financial markets in South Korea and overseas.
Yoo said the recent correction has made US growth stocks more attractive. The S&P 500’s 12-month forward price-to-earnings ratio has fallen to about 19 times, back to its 10-year average, while corporate earnings forecasts remain firm.
“Fundamentals are solid, but sentiment has weakened. Given valuations and investor sentiment, this is a time to take another look at the Nasdaq and growth stocks.”
He does not view high interest rates as severe enough to trigger a broader financial-market crisis. Yoo cited long-term rates of around 5% a year, which he said are not significantly out of line with economic conditions when measured against US real growth and inflation. He also pointed to continued growth in lending and credit.
Yoo said the impact from any unwinding of the yen carry trade should be limited. In his view, Japan’s rate hikes have already been priced in by markets to some extent, while speculative net short positions in the yen have fallen to about half their 2024 level.
“The shock was bigger in 2024 because Japan’s rate hikes were not fully anticipated. The amount left to unwind is smaller now, so the chances of a shock on a similar scale are low.”
Yoo identified the November midterm elections as a key turning point for US stocks. He said markets in midterm election years have typically been weak through the third quarter before rebounding in the fourth.
“This year, the correction could last longer because rate hikes are also in play, but the market is highly likely to regain strong momentum after November.”
Among promising sectors, he singled out optical communications. “Copper cables may be sufficient for connections between accelerators. But for scale-out links between racks or scale-across links between data centers, copper alone is not enough. Optical technology has ample room to grow.”
For individual investors, Yoo said the focus should be on shifts in the investment thesis rather than short-term price swings. “You should not make trading decisions simply because prices have risen or fallen. What determines the time to sell is not the price, but a change in the investment rationale.”
Ko Song-hee, Korea Economic Daily reporter hgsong@hankyung.com

Korea Economic Daily
hankyung@bloomingbit.ioThe Korea Economic Daily Global is a digital media where latest news on Korean companies, industries, and financial markets.