Summary
- The direction of New York stocks will likely be determined by the PCE price index and the September employment report in the U.S.
- A stronger-than-expected PCE reading could raise the prospect of additional rate hikes, higher U.S. Treasury yields and a stronger dollar, creating headwinds for technology and growth stocks.
- In China, investor sentiment could hinge on the manufacturing PMI and details of the U.S.-China trade talks, especially for exporters and cyclical stocks.
Forecast Trend Report by Period

US PCE, jobs; China PMI, trade talks
Inflation or growth? Key indicators for New York and Shanghai stocks
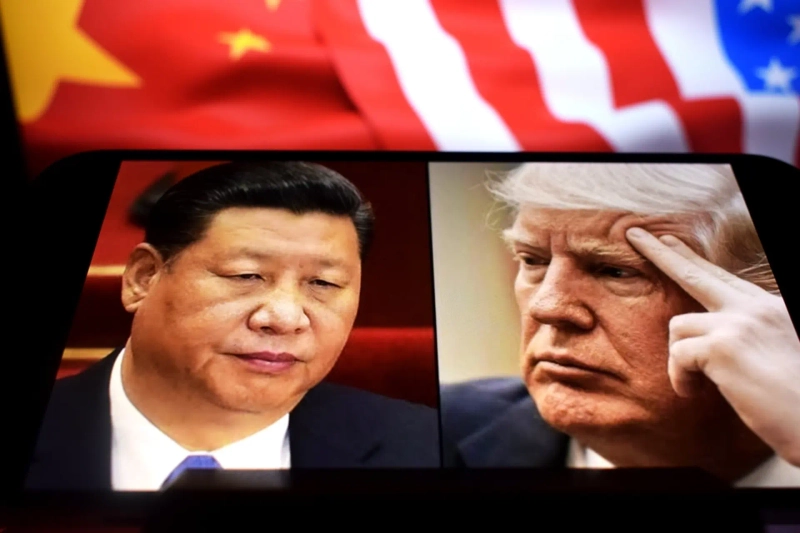
Wall Street's direction this week, from Sept. 28 to Oct. 2, will likely hinge on follow-up announcements from the U.S.-China summit, the August personal consumption expenditures price index and the September employment report.
The U.S. is set to release additional details on the outcome of its trade talks with China on Sept. 28. Investors will focus on which non-sensitive goods will be included in the reciprocal tariff cuts covering $30 billion agreed at the summit, when the measures will take effect, whether agricultural market access will be expanded and China's plan to buy U.S. coal.
Among economic releases, the PCE price index due on Sept. 30 will be a key focus for investors. The PCE price index is the inflation gauge the Fed uses as its benchmark. Economists expect the August reading to rise 0.3% from the previous month and 3.7% from a year earlier. Core PCE, which excludes volatile food and energy prices, is forecast to increase 0.3% on the month and 3.3% on the year.
The key question is how far the data deviates from forecasts. If the PCE reading comes in above expectations, concerns could grow that inflation pressure, which has recently picked up again, is becoming entrenched, bringing the prospect of additional rate hikes back into focus. A hotter-than-expected report could also lift Treasury yields further and strengthen the dollar, weighing on technology and growth stocks.
The September employment report, due on Oct. 2, is also expected to draw close attention. The unemployment rate is forecast at 4.1%, while nonfarm payrolls are estimated to have increased by 80,300 from the previous month. In August, nonfarm payrolls jumped by 162,000, reaffirming the strength of the labor market.
If September job growth significantly exceeds market expectations and the unemployment rate stays at 4.1% or lower, investors would likely interpret that as a sign the labor market remains firm. That would give the Fed more room to stay focused on curbing inflation.
In China, the main event for stock investors will be the official September manufacturing purchasing managers index due on Sept. 30. China's manufacturing PMI rose to 49.8 in August from 49.2 the previous month.
If the September PMI climbs above 50, markets could take that as a sign that China's manufacturing sector has returned to expansion. In particular, if new orders, output and export orders all improve, investor sentiment could recover, especially in cyclical shares, industrials and materials stocks.
If the PMI falls back to the low-49 range or new orders weaken, concerns could intensify that the recovery in domestic demand is being delayed. That could also revive expectations for additional stimulus.
As in New York, details of the U.S.-China trade talks due on Sept. 28 will be a key driver of the near-term direction of Chinese stocks. If the tariff-cut list is broader than expected, implementation comes sooner and plans to expand trade in agricultural products, energy and consumer goods are spelled out, sentiment could improve, led by exporters and cyclical shares.
If the announcement merely reaffirms the existing agreement, or if there is no progress on core issues such as rare earths and restrictions on advanced technology, disappointment-driven selling could emerge.
China's stock market will be closed for the National Day holiday from Oct. 1 through Oct. 7.
Kim Eun-jung, Beijing correspondent kej@hankyung.com

Korea Economic Daily
hankyung@bloomingbit.ioThe Korea Economic Daily Global is a digital media where latest news on Korean companies, industries, and financial markets.