PiCK
Min Byung-duk Says Crypto Tax Should Follow Legal Framework at EastPoint: Seoul 2026
Summary
- Rep. Min Byung-duk said launching crypto taxation early next year would be premature and that South Korea should first establish the institutional framework, including a basic law.
- Min said investors would see the system as unfair unless tax-loss carryforwards are allowed for at least five years so investment losses can be deducted from gains.
- Min said a won stablecoin is needed to support domestic financial stability, reduce international remittance costs and create new businesses and services.
Forecast Trend Report by Period

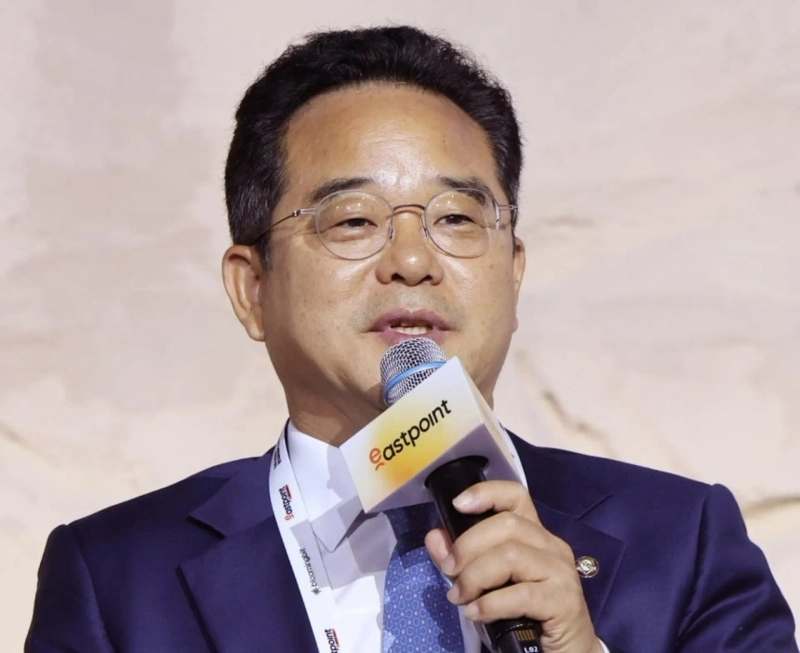
"South Korea has yet to enact even a basic law on virtual assets, or cryptocurrencies. I don't think it is right to impose taxes before that framework is in place."
Min Byung-duk, a lawmaker with the Democratic Party of Korea, made the remarks on Sept. 28 at the Web3 private conference EastPoint: Seoul 2026 at the Grand InterContinental Seoul Parnas in Seoul's Gangnam district. He later took the stage for a panel discussion with Kang Byung-jin, head of legal at Hashed.
Min said implementing virtual-asset taxation early next year would be premature. The principle that income should be taxed is valid, he said, but authorities must be able to determine exactly how income was generated and how much was earned. Proper taxation also requires a clear grasp of both domestic and overseas transactions, he added, and overseas trades are not easy to track accurately.
He also raised the need for a tax-loss carryforward system that would allow investment losses to be deducted from future gains. Min has recently said that, if virtual-asset taxation is introduced, losses should be allowed to be carried forward for at least five years. If an investor incurred losses last year but posted gains this year, there also needs to be a system for reflecting those losses, he said. Taxing only gains generated in a given year without recognizing losses could strike investors as unfair.
On won-denominated stablecoins, Min said they are "absolutely necessary." Stablecoins are tied to monetary sovereignty, he said, and a won stablecoin could help safeguard the stability of South Korea's financial system while expanding payment use cases overseas.
He said demand would be sufficient. Large companies such as Samsung conduct numerous international remittances and settlements with overseas affiliates within their groups, he said. Converting even Korean companies' international transfers into won stablecoins could deliver significant cost savings. He added that stablecoins could sharply reduce card-fee burdens for small merchants and self-employed business owners. If the stablecoin market opens in earnest, new businesses and services that are difficult to imagine today could also emerge, he said.
Min also took aim at the so-called "51% rule," under which stablecoin issuance would be limited to entities controlled by the banking sector. A stablecoin does not become safe simply because a bank holds a 50% plus one-share stake, he said. The core of stability lies in how reserve assets are managed and how risks are supervised.
The digital-asset market can develop more fully only if banks and fintech companies each take on the roles they do best and adopt one another's strengths, Min said. If banks approach the market solely from the standpoint of protecting their existing turf, it will be difficult to build global competitiveness, he added.
Bae Tae-woong, Korea Economic Daily reporter / Lee Jun-hyung, Bloomingbit reporter

Korea Economic Daily
hankyung@bloomingbit.ioThe Korea Economic Daily Global is a digital media where latest news on Korean companies, industries, and financial markets.