"Stablecoins Are the Next Version of Money" and Will Catch On First in Emerging Markets, Speakers Say at EastPoint: Seoul 2026
Summary
- Stablecoin payments are expected to spread first in emerging markets and the cross-border remittance market, helping reduce transaction costs and settlement times.
- Over the next three years, the expansion of on-chain payments is likely to be led by emerging-market fintech companies, potentially creating new markets.
- Stablecoins are a more advanced form of money that can improve payment efficiency through 24-hour operation and more efficient regulatory compliance.
Forecast Trend Report by Period

More useful in countries with weak interbank networks
Fintechs and cross-border users to drive the next wave
Stablecoin payments are set to gain traction first in emerging markets and the cross-border remittance business, where existing financial networks are less developed, speakers said. In countries with weak interbank connections, money can move around the clock, cutting transaction costs and settlement times.
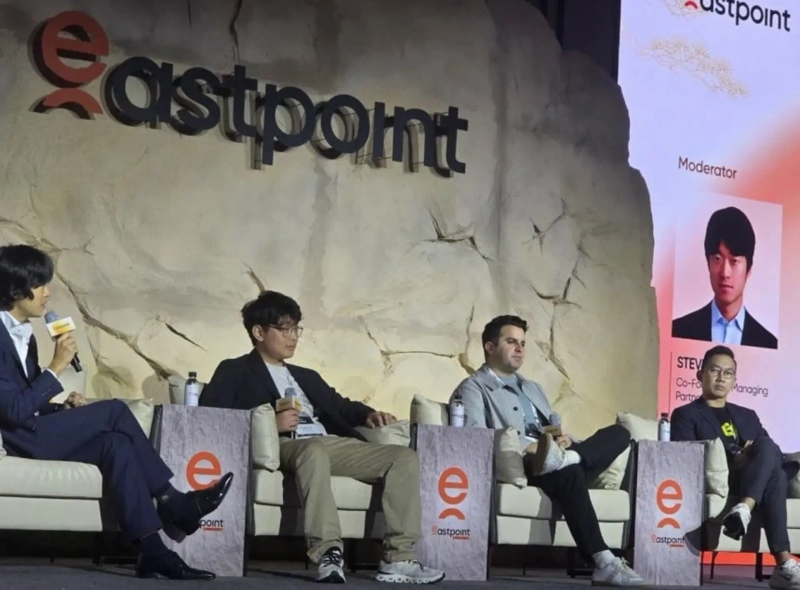
The outlook was discussed at EastPoint: Seoul 2026, a global private Web3 conference held on September 28 at the Westin Seoul Parnas in Seoul's Samseong-dong. The session focused on stablecoins' payment efficiency, regulatory compliance and the path of future market adoption.
Participants were Arnold Lee, chief executive officer of Sphere Labs, Jason Nay Win, Asia-Pacific CEO of Mesh, and Zahir Ebtikar, chief strategy officer of Plasma.
Lee identified countries with underdeveloped correspondent banking relationships as the markets where stablecoins have the greatest utility. In the U.S. and Europe, where banking networks are tightly connected, existing remittance systems can move funds relatively smoothly. Between emerging markets, by contrast, securing intermediary banks can take significant time and money.
"In countries with strong interbank connectivity, the incremental benefit of stablecoins may be limited," Lee said. "But in countries where financial networks are not sufficiently built out, stablecoins can provide real efficiency."
Using stablecoins as an intermediary payment instrument can simplify a complex cross-border transfer into two local transactions, he added. The process involves converting local currency into a stablecoin in the sending country and then converting it back into local currency in the receiving country. Instead of routing through multiple correspondent banks across borders, blockchain connects the financial networks of the two regions.
Nay Win said the appeal of stablecoins extends beyond lower remittance fees. Traditional finance is constrained by national business days and time zones, delaying transfers, while stablecoins can be transacted on weekends and holidays, increasing the speed of capital turnover.
"Financial institutions need substantial staffing and expense to run existing payment systems," he said. "Stablecoins can process transactions transparently and operate 24 hours a day without an organization of the same scale."
He said stablecoins should be viewed not as a separate virtual asset, but as a more advanced form of money. Ultimately, users may not even realize they are using stablecoins.
The panel also cited reducing duplication in regulatory compliance as a key challenge. Because a single transaction can involve multiple financial institutions and payment providers, the same know-your-customer, or KYC, procedures are often repeated at each institution.
Lee said inefficiencies arise when regulated entities carry out customer verification and enhanced due diligence at every stage of a transaction. Blockchain could make it possible to share one institution's verification results with another while protecting personal data. He added, however, that the strictest regulatory obligations should apply to financial firms at the entry and exit points where stablecoins are exchanged for fiat currency.
Ebtikar said it would be difficult for any single blockchain to handle all stablecoin transactions. Users and businesses require different transaction speeds, costs and regulatory conditions, meaning dedicated blockchains and payment services connecting multiple networks will need to develop in tandem.
The speakers agreed that for retail users, convenience matters more than which blockchain is being used. The priority is to create an environment in which consumers can send money faster and more cheaply without having to navigate complex KYC procedures or choose a blockchain themselves.
They also said the expansion of on-chain payments over the next three years is likely to be led not by traditional banks or unregulated crypto firms, but by emerging-market fintech companies with some level of financial licensing. New markets could form as stablecoins connect countries with weak interbank links.
Young people who move frequently between countries were also identified as a key user group. "Online accounts and social media stay with you when you relocate, but financial accounts have to be opened and closed each time you move to another country," Nay Win said. "Stablecoins will allow financial services to be used across borders just like other digital services."
Park Si-on, reporter / Hwang Doo-hyun, Bloomingbit reporter

Korea Economic Daily
hankyung@bloomingbit.ioThe Korea Economic Daily Global is a digital media where latest news on Korean companies, industries, and financial markets.