AI Lending Pipeline Starts to Run Dry: Park Shin-young’s Pre-Market Briefing
Summary
- AI-related debt financing hit a record $460 billion, while loan rates rose into double digits, sharply worsening funding conditions.
- Rates on top-rated data-center ABS, CDS costs, and investment-grade technology bond yields have all risen, expanding credit risk at major AI companies including Oracle, SpaceX, Nvidia, Meta and Broadcom.
- Moody’s said the risk of distress in private credit markets could rise because of PIK interest, a heavy maturity wall in 2027-2029 and delay risks in AI data-center projects, underscoring the need to focus on AI investments’ cash-generation ability.
Forecast Trend Report by Period

1. Fed pause seen as likely, while Wall Street splits on strategy
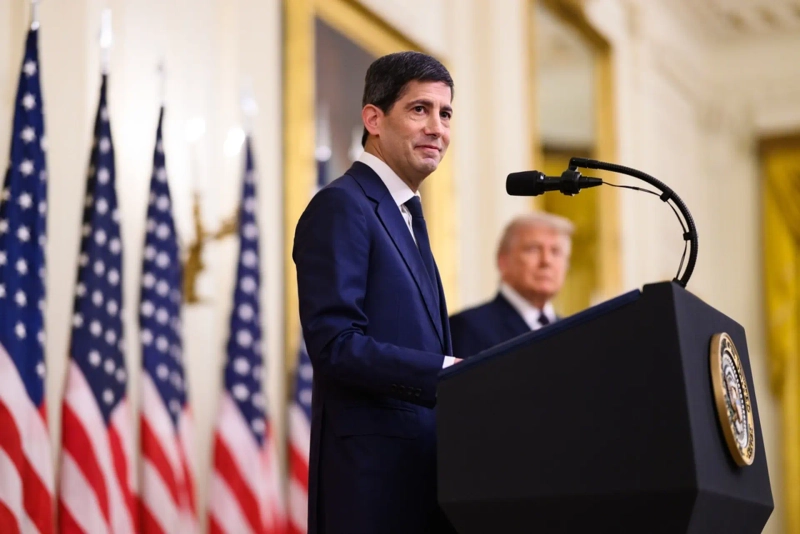
Wall Street is divided on how to invest ahead of the Federal Reserve’s October Federal Open Market Committee decision. Markets are pricing in roughly a 90% chance that the Fed will leave its benchmark rate unchanged. The key question is what Fed Chair Kevin Warsh says at his press conference about the future path of monetary policy.
The Fed is due to announce its rate decision on Oct. 28. The benchmark rate currently stands at 3.75% to 4.00%. Gregory Daco, chief economist at EY-Parthenon, said Warsh will need to make a convincing case for holding rates steady even as inflation pressures persisted after September’s rate increase. The Fed must also dispel any perception that monetary policy was shaped by politics ahead of the midterm elections. If the explanation falls short, bond markets could sell off.
Liz Thomas, chief market strategist at SoFi, argues that investors should increase exposure to commodities regardless of the Fed’s rate path. She cited the commodities ETF PDBC as a hedge against inflation and extreme weather. The fund has gained 51% this year.
Phil Rosen, chief market strategist at Sylva, recommended the energy ETF XLE, citing rising power demand from the AI industry and a prolonged war involving Iran. The S&P 500 energy sector has climbed 55% this year, the best performance among all sectors. Shares of Marathon Petroleum, Valero Energy, Phillips 66 and APA have more than doubled since the start of the year.
Some investors still favor defensive sectors. George Achempon, founder of Capitalwize, said investors should focus on companies that can keep growing even without rate cuts. He recommended the consumer-staples ETF XLP and the healthcare ETF XLV, citing stable demand and cash flow. Rosen also named Eli Lilly as a preferred stock because of growth in the GLP-1 obesity-drug market and the company’s ability to use AI.
Ultra-wealthy investors are concentrating on AI infrastructure. R360, a network for investors with net worth above $100 million, is backing companies that supply power, capital and data centers rather than trying to pick the ultimate AI winner. Its top targets include power provider Constellation Energy, investment firm Blackstone and data-center operator Equinix.
The mood is different at Long Angle, a group for investors with net worth between $5 million and $100 million. Members are increasingly wary of rich valuations in AI-related shares. In a survey of about 200 members, 59% said AI stocks were overvalued. Another 52% said they were increasing allocations to safe-haven assets. Concern has also grown over sharply rising AI names such as SanDisk and Oracle, while appetite for Tesla and SpaceX has weakened.
2. Anthropic holds $131.7 billion in cash, ranking third among U.S. companies
AI company Anthropic has become the third-largest holder of cash-like assets among U.S. corporations. Still, its future computing-related contractual obligations far exceed its cash pile, raising the prospect that it may need additional funding.
According to Anthropic’s initial public offering filing with the U.S. Securities and Exchange Commission, cash and cash equivalents totaled $112.4 billion at the end of June, while short-term investments stood at $19.3 billion. That brought the total to $131.7 billion.
Only Berkshire Hathaway and Alphabet hold more cash-like assets among non-bank U.S. companies, according to CNBC and S&P Capital IQ. Anthropic’s cash exceeds that of Amazon, Meta and Microsoft. It is also larger than the combined cash-like assets of Nvidia and Apple.
Anthropic is poised to raise another large sum through its IPO. The Wall Street Journal and other outlets have reported that the offering could bring in more than $100 billion. If all of that went to the company, cash-like assets could exceed $230 billion. The split between newly issued shares and stock sold by existing holders has not been finalized.
Anthropic has raised a total of $141 billion in private markets over roughly six years since its founding. That underscores how much money has been poured into AI model development and computing infrastructure.
The issue is how much it still has to spend. As of the end of June, Anthropic had $321.4 billion in future lease obligations and $265.6 billion in fixed or minimum-payment contract commitments. The total came to $587 billion, about 4.5 times its cash-like assets at the same point.
The company also took on roughly $245 billion in additional payment obligations from contracts signed or amended after the end of June. On a simple sum, that would bring the figure to $832 billion. Anthropic has not disclosed a consolidated total under the latest contract terms, so that number should not be treated as final. These are contractual commitments paid over time, not debt that must be repaid immediately.
Anthropic’s computing and infrastructure costs in the first half totaled $8.95 billion. The company said it typically secures computing capacity 12 to 18 months before actual use and begins recognizing the related expense once that capacity becomes available. That means actual costs could rise sharply in the periods ahead.
That helps explain why Anthropic is pursuing more financing despite its huge cash reserve. If revenue and cash flow from AI services do not increase as much as expected, the company may have to keep relying on external funding to support expansion.
3. AI lending surges as banks grow cautious
Corporate lending at U.S. banks is rising quickly as construction of AI data centers accelerates. But as large banks tighten risk controls, companies are expanding their funding channels into bond markets.
Corporate lending at the top 25 U.S. banks rose about 10% in the third quarter from a year earlier, The Wall Street Journal reported. Excluding the pandemic period, that marks the fastest pace of growth in more than a decade. Borrowing tied to data-center spending by Microsoft and Meta, along with financing needs at related construction firms, drove the increase.
Banks have a chance to boost interest income as lending grows, but the stock market’s verdict has been more restrained. The KBW Nasdaq Bank Index is up about 5% this year, trailing the nearly 13% gain in the S&P 500.
JPMorgan Chase has stressed that risk management is critical because money is reaching the AI sector through multiple channels. Large banks are wary of extending additional loans to companies that have already borrowed heavily, such as Oracle. Wells Fargo has also said it is closely examining who the actual users of data centers are and who is ultimately responsible for repaying the loans.
The boom in AI investment is also affecting regional banks. When major banks lend directly to data-center developers, smaller lenders are financing construction firms and equipment suppliers tied to those projects. Fifth Third Bancorp said it is lending not to data-center developers themselves but to the companies actually building the facilities.
There is also a downside risk. If AI investment slows, construction companies could be left burdened by equipment spending and expanded payrolls. PNC Financial acknowledged that a slowdown in AI investment could weaken overall loan growth across the banking sector.
The gap between AI-related investment and spending in other parts of the U.S. economy is also widening. Power-related construction spending in August rose about 9% from a year earlier, while residential construction spending fell about 5%. KeyCorp said years of underinvestment in U.S. power infrastructure mean grid expansion could continue even if AI spending cools.
As banks grow more cautious on AI-related lending, companies are increasingly raising money directly through bond issuance. That is shifting part of the credit risk once borne by banks to bond investors and other financial firms. It also helps explain why prices for some AI-related corporate bonds have fallen and funding costs have risen.
4. AI loan rates top 10% as warnings mount over funding strains
Financing needs for AI data-center investment are surging, but warnings are growing that financial firms and investors may be nearing the limits of what they can provide. Bloomberg reported that global corporate AI-related debt financing reached a record $460 billion this year.
AI-related companies will need trillions of dollars more over time. Bloomberg, citing interviews with more than 30 finance professionals, reported that funding conditions have become far tougher than they were just a few months ago.
At least 18 data-center financings in the junk-bond and leveraged-loan markets are carrying double-digit interest rates. JPMorgan and Goldman Sachs had to cut the price and lift the yield to more than 11% a year to sell a $5 billion loan for AI cloud company Volta Infrastructure to investors.
Rates on top-rated data-center asset-backed securities have also climbed, rising from below 5% at the start of the year to around 7% recently. Morgan Stanley said financing multibillion-dollar data-center construction becomes much harder once rates approach 8%.
Citadel Securities warned that risk in the AI lending market could spread from small and midsize data-center companies to major technology firms. If a data-center company cannot repay its borrowings, that could also hurt large tech companies that backed the financing or signed long-term purchase agreements.
Tucker Roberts, an analyst at Citadel, said the more important question now is not the credit quality of large technology companies themselves, but whether there are enough investors willing to absorb the vast amount of debt linked to them.
Credit-default-swap markets are also signaling rising risk among AI-related companies. Bloomberg reported that Oracle’s CDS costs hit a record high last week. CDS costs for SpaceX, Nvidia and Meta have also risen sharply. Concern is also building over the credit risk of major AI companies including Broadcom.
The average yield on investment-grade technology bonds has risen to about 6%, up 1.4 percentage points from a year earlier. Even top-tier Big Tech companies are borrowing at higher costs than before.
Investors are also worried about contract cancellations tied to construction delays at data centers. Some data-center contracts allow customers to cancel if a project is delayed by more than three months or 180 days.
One hedge fund declined to invest after confirming a clause that allowed customers to walk away if data-center construction was delayed by more than three months. Oracle also notified counterparties last month that force majeure terms could allow it to postpone payments if construction at its New Mexico data center is delayed.
Large investment firms including Oaktree Capital, KKR and Carlyle are becoming more selective as they weigh technology shifts, construction delays, power shortages and permitting issues.
The Wall Street Journal said banks are acting more cautiously than they did before the 2008 financial crisis by setting lending limits for specific borrowers and offloading riskier loans to other investors. But the migration of risk from banks into private credit and bond markets has become a new source of concern.
5. Moody’s warns of trouble in AI private credit
AI-related lending has become a major growth engine for private credit, but Moody’s warned that default risk could rise as large volumes of debt come due between 2027 and 2029.
Moody’s said a substantial amount of loan maturities, including AI-related debt, will come due in private credit markets from 2027 through 2029. If companies fail to repay existing debt and are forced to refinance, higher interest rates could leave them with a heavier burden.
One point drawing particular attention is how interest is being paid. Of the 607 companies tracked by Moody’s, about 17% are paying part of their interest not in cash but with additional debt. That structure is known as payment-in-kind, or PIK, interest.
For example, if a company borrows about $7.2 million and owes annual interest of about $720,000, it would normally pay that amount in cash. Under a PIK structure, however, the interest is added to principal instead, increasing the debt to about $7.9 million. That reduces immediate cash outflows but leaves the borrower with a larger debt load over time.
Moody’s identified 2028 as a particularly vulnerable year. AI data-center projects often require heavy upfront spending on construction and equipment, while revenue comes later. If facilities are delayed or customer demand falls short of expectations, borrowers may not generate enough cash to repay principal and interest.
The AI sector’s circular financing structure is also a risk factor. A semiconductor company may invest in a data-center operator, which then uses that company’s chips. If that pattern repeats, both semiconductor sales and data-center investment can rise at the same time.
But if a data-center company runs into trouble, lenders could suffer loan losses while chipmakers take a hit from weaker sales and investment losses at the same time. That creates a channel through which stress at one company can spread to others.
The valuation methods used by private credit funds are another source of concern. Because private credit does not trade daily in public markets, funds often rely on internal models to value loans.
If asset values are not adjusted promptly even as a borrower’s repayment capacity deteriorates, investors may recognize the true scale of loss risk too late. In private credit funds with limited redemption rights, the gap between stated valuations and recoverable value may not become clear until assets are actually sold.
Moody’s warning highlights that what matters is not just how fast AI investment is growing, but how much cash companies are actually generating. If cash flow from running data centers is not enough to cover principal and interest, more investment could simply add to debt burdens.
6. Google expands AI chip sales, stepping up its challenge to Nvidia
Google is broadening its challenge to Nvidia by supplying its in-house AI semiconductor, the TPU, to outside cloud companies. On Wall Street, some analysts project Google’s TPU revenue could reach as much as $99 billion next year.
Google is expanding external sales of its TPU AI chips in partnership with Oracle, CNBC reported. The company has been developing TPUs since 2013, but it only began selling them in earnest to outside customers in the second quarter of this year.
Until now, Google had focused on bundling its own chips, AI models and cloud services. It is now trying to widen the market by selling TPUs even to companies that do not use Google Cloud.
The TPU push is unfolding alongside rapid growth at Google Cloud. Wall Street expects Google Cloud’s third-quarter revenue to rise about 90% from a year earlier. That would be faster than the 82% growth recorded in the second quarter.
Google Cloud posted $25 billion in second-quarter revenue, below Amazon Web Services at $42 billion and Microsoft Azure at $29 billion. But among the three, Google is growing the fastest.
Wall Street also expects TPU revenue to rise quickly. TD Cowen projects Google’s TPU revenue will increase from $9.4 billion in the second half of this year to $62.5 billion in 2027.
Wells Fargo estimates TPU revenue at about $9 billion in the third quarter of this year and $99 billion next year. Forecasts vary widely across brokerages, and actual revenue will depend on when supply agreements are carried out.
Google’s edge on TPUs comes from cost. Semiconductor research firm SemiAnalysis estimates the total cost of ownership and operation for Google’s latest Ironwood TPU server is about 44% lower than for Nvidia’s GB200 server.
Google Cloud Chief Executive Officer Thomas Kurian said the payback period for the company’s in-house AI servers is less than two years. Servers using internally developed chips have a payback period roughly half that of conventional AI servers.
Still, expanding external TPU sales could weigh on profitability. TD Cowen estimates the operating margin for the TPU sales business at about 20%. That is below Google Cloud’s overall operating margin of about 35%, meaning broader TPU sales could drag down margins across the cloud division.
Google’s TPU customers include companies that also compete with it in AI models. Anthropic signed a contract worth tens of billions of dollars with Google last year and agreed to use as many as 1 million TPUs.
OpenAI is also seeking to buy Google TPUs. That leaves Google as a rival to Anthropic and OpenAI in AI models while also acting as a supplier in semiconductors.
The TPU expansion is also an important growth opportunity for Broadcom. Broadcom is a key partner in Google’s TPU development.
Broadcom this week disclosed a $63 billion financing structure backed by Blackstone and three major banks. Under the arrangement, a financing vehicle buys TPUs and networking equipment from Broadcom and leases them to Anthropic for five years.
William Blair said that financing would cover about half of Anthropic’s funding needs in 2027. Google’s TPU sales push is now feeding not only chipmakers and AI model developers, but also large-scale financing businesses on Wall Street.
7. Ackman says buy companies you would hold for 20 years
Billionaire hedge fund investor Bill Ackman, chief executive officer of Pershing Square Capital Management, said investors should own companies that can sustain their competitive edge and generate cash over long periods.
In a podcast interview released on Oct. 28 with Nicolai Tangen, chief executive officer of Norges Bank Investment Management, the manager of Norway’s sovereign wealth fund, Ackman said investors should buy companies whose value would endure over the long term even if the stock market shut down for 20 years.
He said the focus should be on lasting competitiveness and cash-generation ability, not short-term stock gains. Ackman said he favors companies that can sustain high growth for long periods without needing to reinvest most of the cash they generate back into the business.
He also said investors need to be able to forecast a company’s cash flow over the next 10 to 20 years with reasonable confidence to assess its value. He tries to avoid businesses that are heavily dependent on external variables beyond management’s control, such as commodity prices, interest rates and regulatory shifts.
Pershing Square has concentrated its investments in a small number of companies, including Amazon, Microsoft, Meta, Brookfield, Uber, Visa and Mastercard.
Ackman said there may be 200 to 300 excellent companies around the world, but chances to buy them at attractive prices are much rarer. Finding a good business matters, but so does paying the right price.
He also advised investors to test their conviction by seriously reviewing the arguments made by short sellers with the most critical views on a company. If those arguments can be rebutted logically, confidence in the investment case can rise. If they are persuasive, investors should revise their views.
Ackman said AI is affecting every company, and investors need to distinguish between businesses that will benefit from it and those whose existing models are under threat.
He said he bought Amazon after President Donald Trump announced tariffs, and bought Meta and Microsoft when their shares fell on concerns over rising AI investment.
Pershing Square’s performance has recently come under pressure as concerns over AI capital spending have intensified. Pershing Square USA Ltd., the U.S.-listed closed-end fund that trades under the ticker PSUS, has risen 42% over the past three months but fallen 16% so far in October. Meta has also dropped 14% in October even after reporting earnings that beat expectations, as investors focused on the burden of AI spending.
Ackman lost about $400 million on his Netflix investment in 2022 and sold the stake. But in August, he disclosed that he had started investing in Netflix again.
Park Shin-young, New York correspondent, Hankyung.com, nyusos@hankyung.com

Korea Economic Daily
hankyung@bloomingbit.ioThe Korea Economic Daily Global is a digital media where latest news on Korean companies, industries, and financial markets.