Tokenized Stock Market Grows 5.3-Fold This Year; 82% Is in Non-Voting US Offshore Products
Summary
- The value of tokenized stocks circulating on-chain rose 5.3 times from the start of the year to reach $3.58 billion.
- It said 82% of outstanding issuance consists of non-voting US offshore wrapper products, which provide only stock price-linked returns.
- It said domestic rulemaking should take into account rising trading in overseas-issued tokens based on Korean stocks.
Forecast Trend Report by Period

The market for tokenized stocks has grown 5.3-fold this year, but 82% of outstanding issuance is in US offshore products that carry no voting rights, according to a new report. The study also called for South Korea to design rules that take into account tokens based on Korean shares but issued overseas.
DigitalX Research Center, the digital-asset investment platform of Mirae Asset, said on Oct. 29 that it had published a report titled "Tokenized Stocks: From Gray Zone to Institutional Framework."
According to the report, the value of tokenized stocks circulating on-chain reached $3.58 billion as of Oct. 23, or 5.3 times the level at the start of the year. That far outpaced the 54% growth in the broader real-world asset, or RWA, market over the same period.
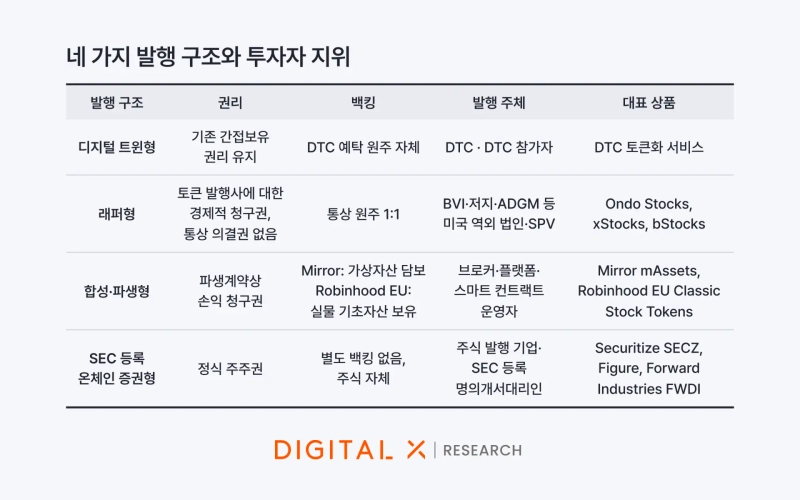
Holding such tokens does not necessarily grant the same rights as owning the underlying shares. The report classified tokenized stocks into four issuance structures: digital twin, SEC-registered on-chain securities, wrapper, and synthetic or derivative. The first two preserve rights to the underlying shares, including dividends and voting rights. The others provide only returns linked to stock prices and do not carry voting rights.
It said 82% of outstanding issuance currently consists of US offshore products from Binance, Ondo Finance, xStocks and Robinhood, most of which fall into the wrapper category.
The US is also taking steps to bring the market into the regulatory mainstream. The report said the Depository Trust Co., a central securities depository, processed live trades in a tokenization pilot in July, while the Securities and Exchange Commission granted exemptive relief in September for an on-chain trading venue. Still, the research center said both measures remain at an early stage and it is too soon to conclude they have led to a broad expansion in distribution.
The scope of South Korea's domestic rules was also identified as a challenge. Amendments to subordinate regulations have been put up for legislative notice ahead of the revised Electronic Securities Act taking effect in February 2027, but they do not address tokenized stocks issued overseas. With trading abroad increasing in tokens based on Korean stocks such as SK Hynix, the report said the regulatory framework should account for that activity.
"If the infrastructure to issue tokenized stocks in South Korea is not in place, tokenized trading in Korean stocks will first take hold outside the scope of domestic regulations," Chung Ji-sung, a research fellow at DigitalX Research Center, said. He added that institutionalizing the tokenized stock market depends less on rushing issuance than on linking rights, liquidity, collateral and reference prices under a consistent set of rules.

YM Lee
20min@bloomingbit.ioCrypto Chatterbox_ tlg@Bloomingbit_YMLEE