SK Hynix Price Targets Span 1.65 Million Won to 4 Million Won, Angering Retail Investors
Summary
- Domestic brokerages set SK Hynix target prices in a wide 1.65 million won to 4 million won range, underscoring a sharp gap in their outlooks.
- Multiple brokerages maintained or raised buy ratings and high price targets, citing HBM demand, a memory supply shortage, and the company’s shareholder return policy.
- Some firms kept more conservative price targets and hold ratings, citing a slowdown in AI investment and PER directionality, fueling debate among retail investors over the credibility of brokerage reports.
Forecast Trend Report by Period

Brokerages Diverge Sharply on SK Hynix Price Targets
SK Securities, Kyobo Set 4 Million Won Targets; BNK Investment & Securities Sees 1.65 Million Won
‘Trust Can Recover Only if Post-Report Verification Becomes Standard’
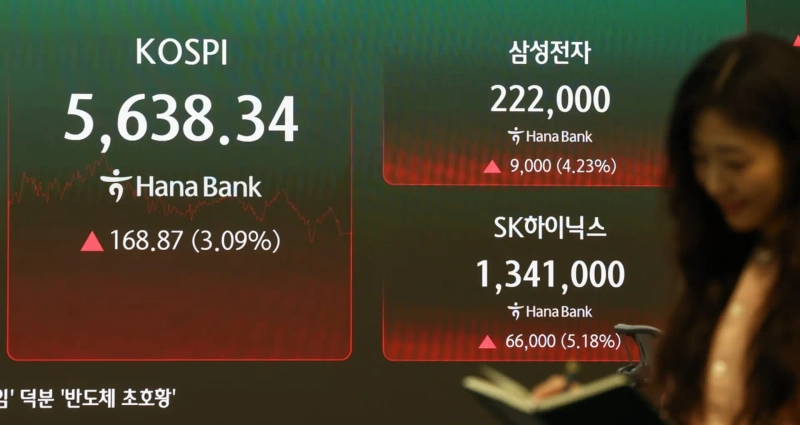
Domestic brokerages have published widely differing price targets for SK Hynix despite the company’s record earnings and shareholder return plan, adding to confusion among investors. Some firms have set targets as high as 4 million won, citing demand for high-bandwidth memory, or HBM, while others have put the stock at 1.65 million won, pointing to a possible slowdown in artificial intelligence spending. Retail investors are increasingly voicing frustration over the basis for those forecasts and the credibility of the analysis.
According to the financial investment industry on October 29, major South Korean securities firms set SK Hynix price targets in a range of 1.65 million won to 4 million won after the company’s third-quarter earnings release. Most maintained buy ratings, while some raised their targets.
SK Hynix reported third-quarter revenue of 104.6 trillion won, up 327.9% from a year earlier. Operating profit surged 632.1% to 83.3 trillion won, and its operating margin reached 79.7%. Higher DRAM and NAND flash prices, along with increased sales of high-value products, helped results top market expectations.
Brokerages also expect fourth-quarter earnings to improve further. SK Securities wrote that deepening memory supply shortages and rising memory prices linked to the initial impact of HBM4, the sixth generation of HBM, offset the decline in the exchange rate and helped SK Hynix deliver earnings above market expectations. The firm forecast fourth-quarter operating profit at 105 trillion won, which would mark the start of the company’s first 100 trillion won quarter.
SK Securities maintained a buy rating and kept its target price at 4 million won. The brokerage said SK Hynix has presented a view that memory demand will remain in a supply-constrained phase through 2030. It also said the strong rationale for AI infrastructure investment and the structure of memory demand point to a period of improving earnings visibility and stability. Kyobo Securities also set a 4 million won target.
BNK Investment & Securities, widely known for conservative target prices, raised its SK Hynix target to 1.65 million won from 1.48 million won. That still leaves a gap of 2.35 million won versus the 4 million won targets from SK Securities and Kyobo Securities. BNK said the increase reflected stronger-than-expected second-half earnings and an HBM price hike expected early next year. It also said the stock appears oversold in the short term relative to earnings, and that sentiment toward AI investment is improving as credit risk in the AI industry has eased following Anthropic’s IPO, supporting a rebound in the shares.
At the same time, BNK maintained its hold rating. The brokerage said momentum in memory demand has slowed since peaking in the second quarter and that trend is likely to continue. It added that a low price-to-earnings ratio trend is also set to persist given AI-sector credit risk and a prolonged high-interest-rate environment.
KB Securities, which has consistently taken a bullish view on semiconductor stocks, cut its SK Hynix target price to 3.5 million won from 4.2 million won. The firm projected fourth-quarter operating profit at 89 trillion won and maintained its buy rating. Even while taking a positive view of the company’s record 100 trillion won shareholder return plan and future industry conditions, it lowered the target by 700,000 won.
IBK Investment & Securities also cut its SK Hynix target to 3.2 million won from 4 million won. The brokerage kept its buy rating and said the stock remains undervalued relative to earnings. It said the lower target did not reflect concern about the memory market outlook, but rather the gap between the target price and the current share price.
Hana Securities maintained its 3.6 million won target and raised its forecast for next year’s operating profit to 464 trillion won. Daol Investment & Securities and NH Investment & Securities estimated fourth-quarter operating profit at 101 trillion won and 102.7 trillion won, respectively. BNK Investment & Securities also forecast operating profit of 103.6 trillion won.
Hanwha Investment & Securities focused on the company’s view that memory shortages could continue through 2030, given the technical difficulty of advanced processes and the time required to build new production facilities. The brokerage said the expansion of long-term supply agreements, or LTAs, supports earnings stability for memory makers, and that the large-scale shareholder return policy also influenced the sector’s assessments. Yuanta Securities raised its target price to 3.7 million won from 3.3 million won.
The stark differences in brokerage analysis have led some retail investors to question the value of such reports. “Does it make sense for target prices on the same SK Hynix stock to range from 1.65 million won to 4 million won?” one investor said. “I can’t tell whether they are analyzing earnings or just attaching the numbers they want.”
The investor added that such wide differences raise doubts about whether brokerages have any consistent analytical philosophy or sense of accountability. “Reading these reports only makes my blood pressure rise,” the investor said.
Another investor criticized brokerages for offering different reasons for raising or cutting target prices while facing no consequences when their forecasts miss. Retail investors are expected to make disciplined judgments, the investor said, yet securities firms themselves fail to provide disciplined analysis on the same company.
An executive at one securities firm said differences in target prices reflect varying assumptions about when the memory cycle will peak and how long AI investment will continue. The issue is not that forecasts diverge. Rather, firms do not adequately disclose the basis for their earnings estimates and fair-value calculations.
The executive added that brokerages should present earnings and stock-price levels under optimistic, neutral and pessimistic scenarios when publishing target prices so investors can make their own judgments. Trust in research reports can recover only when firms establish a practice of verifying after the fact which assumptions on earnings and market conditions changed when forecasts prove wrong.
Kang Kyung-ju, Hankyung.com reporter memory@hankyung.com

Korea Economic Daily
hankyung@bloomingbit.ioThe Korea Economic Daily Global is a digital media where latest news on Korean companies, industries, and financial markets.