AI Bubble Fears Rattle US Stocks; China Braces for Inflation and Export Data
Summary
- The key drivers for US stocks are the consumer price index (CPI), the producer price index (PPI), the possibility of additional tightening by the Fed, and concerns that AI-related stocks are overvalued.
- The CoreWeave earnings report due on November 10 will be closely watched for how cash burn, debt burdens, fundraising plans and the investment schedule could affect AI infrastructure investment and investor sentiment toward AI-related stocks.
- The main variables for Chinese stocks are the CPI, PPI, trade and customs data, sentiment toward export-related shares, demand for raw materials and intermediate goods, the yuan exchange rate, and foreign-exchange market liquidity.
Forecast Trend Report by Period

Focus Turns to CoreWeave Earnings and China Export Data
US Inflation Shock or AI Rebound
Global Markets Hold Their Breath for China’s Trade Report Card
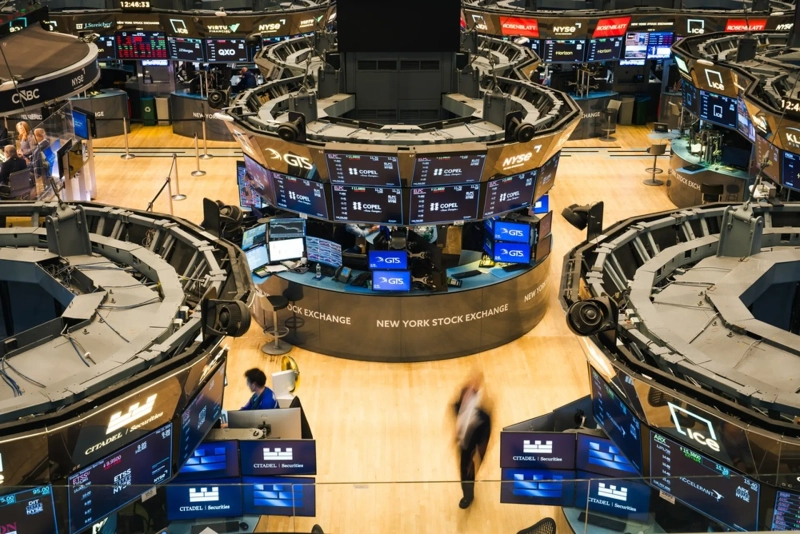
US stocks in New York and Chinese shares in Shanghai are poised for greater volatility this week, from November 9 to November 13, as investors await major economic data from both countries. On Wall Street, the key variables are the US consumer price index and earnings from AI infrastructure company CoreWeave. In Shanghai, investors will look to China’s inflation and trade data for clues on the recovery in domestic demand and the direction of external demand.
In New York, attention is on whether the S&P 500 can rebound after four straight weekly declines and whether the Nasdaq Composite can recover after entering a technical correction. With concerns over elevated valuations in AI-related shares still lingering, stronger-than-expected US inflation could trigger fresh selling in technology stocks.
Investors are closely watching the US October CPI report due on November 10. Markets expect both headline CPI and core CPI, which excludes food and energy, to have risen 0.3% from the previous month. After last week’s employment data showed the US labor market remains resilient, a hotter-than-expected inflation reading could sharpen expectations for further tightening by the Federal Reserve.
The October producer price index is due on November 13. Market estimates call for headline PPI to rise 0.4% from a month earlier and core PPI to increase 0.3%. Some PPI components feed into the personal consumption expenditures price index, the Fed’s preferred inflation gauge, making the report an important indicator for the monetary-policy outlook.
CoreWeave’s third-quarter results, due after the close on November 10, will also be closely watched as a test of the sustainability of the boom in AI infrastructure investment. Investors are focusing less on revenue growth than on cash burn and borrowing pressures tied to heavy capital spending.
Uncertainty has also increased over new facility construction and power supply after the Democratic Party’s victory in the US midterm elections raised the prospect of tighter data-center regulation. What CoreWeave management says about fundraising plans and its investment schedule during the earnings release is likely to influence sentiment toward AI-related shares.
In Shanghai, the main variables are China’s October CPI and PPI, due on November 9, and trade and customs data expected on November 10. The week’s releases will offer a read on the pace of the domestic-demand recovery, pricing pressure in manufacturing and the strength of export growth.
Markets expect China’s October CPI increase to slow to 0.8%, while PPI inflation is projected to accelerate to 5.2% to 5.3%. If consumer inflation eases while producer prices continue to rise, investors are likely to focus on corporate cost burdens and the pace of the recovery in consumption.
Trade data due on November 10 will also be in focus. In September, China’s dollar-denominated exports rose 36.3% from a year earlier, while imports increased 31%. Investors are watching whether export growth held up in October. Weaker-than-expected exports could hurt sentiment toward export-related shares. By contrast, sustained import growth would provide a gauge of Chinese demand for raw materials and intermediate goods.
Liquidity management by the People’s Bank of China is another market variable. The central bank will raise the reserve requirement ratio on foreign-currency deposits held by financial institutions to 6% from 4%, effective November 15. Investors will be watching the impact on the yuan and foreign-exchange market liquidity.
Kim Eun-jung, Beijing correspondent kej@hankyung.com

Korea Economic Daily
hankyung@bloomingbit.ioThe Korea Economic Daily Global is a digital media where latest news on Korean companies, industries, and financial markets.