Further Delay Isn’t the Only Answer for Crypto Tax; Rules Should Be Refined After Implementation
Summary
- Professor Byun Hye-jung said virtual-asset taxation requires clear legal grounds for taxation and greater predictability, rather than another delay.
- She said repeated tax delays are undesirable and that the system should be refined after implementation through legal interpretation and objection procedures.
- She said issues including crypto investors’ shift overseas, withholding tax on non-residents, CARF, and the collection of overseas transaction data should be reviewed for both effectiveness and taxpayer data protection.
Forecast Trend Report by Period

South Korea should improve its virtual-asset tax regime by establishing clear taxation standards and increasing predictability for taxpayers, rather than opting for another delay ahead of implementation, a professor said.
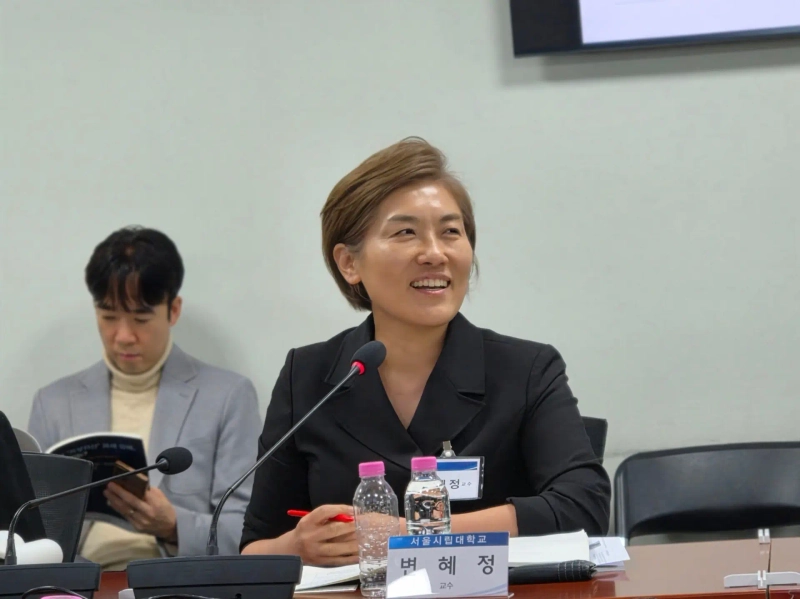
Byun Hye-jung, a professor at the University of Seoul, made the remarks on Oct. 30 at a seminar held at the National Assembly Members’ Office Building in Seoul’s Yeouido district titled, “2027 Virtual-Asset Tax Delay: When Should It Take Effect?” She spoke during a discussion on “The Direction of Virtual-Asset Taxation From the Perspective of Maximizing Taxpayer Welfare.”
Byun said the debate over crypto taxation should distinguish between institutional shortcomings and taxpayer sentiment. While flaws in the system need to be considered and policymakers should listen to taxpayers, it is also necessary to examine whether the voices of virtual-asset traders are being given disproportionate weight, she said.
She also said unclear legal grounds for taxation could increase the burden on taxpayers. Even when explicit grounds are lacking, the National Tax Service may still attempt to levy taxes using existing rules, which could prolong disputes between taxpayers and the authorities. Establishing clear legal grounds would improve predictability and reduce unnecessary disputes, she added.
Byun also addressed the effect of repeated delays on tax administration. She said the current tax system is not perfect, but gaps in the law alone do not justify postponing implementation. Weak points in the framework can be addressed after enforcement through legal interpretation and objection procedures.
On concerns that crypto investors could move overseas, Byun said domestic and foreign investors should be approached separately. She said the effectiveness of withholding-tax rules for non-residents should be reviewed because the actual exercise of taxing rights may be limited by tax treaties. She also proposed considering a tax framework that gives investors incentives to use domestic exchanges in order to discourage a shift to overseas platforms.
Byun also said the Crypto-Asset Reporting Framework, or CARF, is not a prerequisite for implementing taxation. CARF is only an information-sharing framework and does not itself make taxation possible, she said. Because South Korea’s income-tax system is based on taxpayer filing, taxpayers still have a duty to report even if the National Tax Service does not have all transaction data.
Still, she said the National Tax Service should take a cautious approach to collecting overseas transaction data before taxation takes effect. It is necessary to review whether it is appropriate for the agency to secure taxpayers’ overseas transaction data in advance while taxation remains delayed, she said. Administrative convenience should be weighed alongside taxpayer data protection and rights.

Suehyeon Lee
shlee@bloomingbit.ioI'm reporter Suehyeon Lee, your Web3 Moderator.