U.S. Job Growth Seen Rebounding, Boosting Odds of Another Fed Rate Hike
Summary
- Bloomberg reported that expectations for a rebound in U.S. job growth are strengthening the case for another rate hike by the Federal Reserve.
- If October nonfarm payrolls rise and the unemployment rate holds steady, while other labor-market indicators support job stability, the likelihood of additional Fed tightening would increase.
- Even as economists point to rising job losses and weakening labor-market momentum, manufacturing data, trade figures, and third-quarter productivity growth are likely to serve as key gauges of the U.S. economy’s underlying strength.
Forecast Trend Report by Period

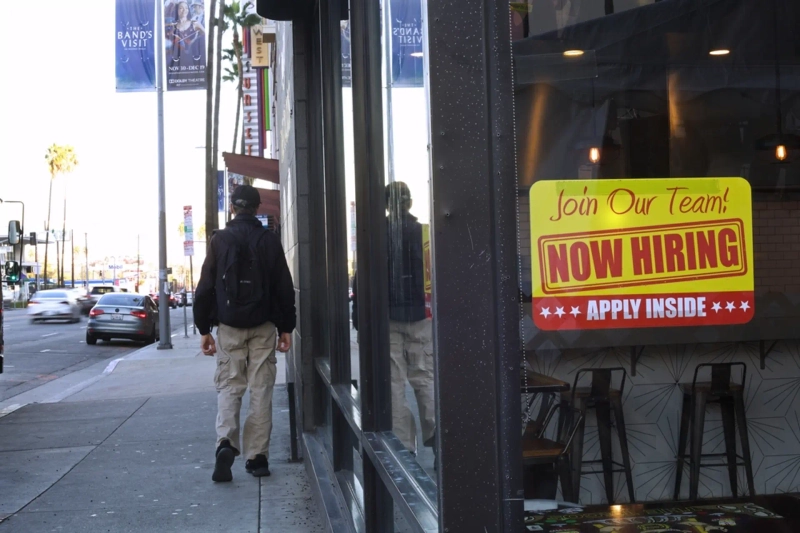
A rebound in U.S. job growth is poised to strengthen the case for another interest-rate increase by the Federal Reserve.
According to Bloomberg on Nov. 31, market experts expect the U.S. Bureau of Labor Statistics to report an increase of 65,000 in October nonfarm payrolls when it releases the data on Nov. 6. That would be more than double the previous month’s gain, while the unemployment rate is forecast to hold at 4.2%.
If the employment data matches forecasts, it would reinforce the view that the U.S. labor market is recovering gradually and increase the likelihood of additional Fed tightening. With inflation pressures still persistent, labor-market stability could give the central bank grounds to continue raising rates in the coming months.
Other labor-market data due this week is also expected to support signs of employment stability. September job openings, due on Nov. 3, are projected to rise slightly, while weekly initial jobless claims, scheduled for Nov. 5, are likely to remain near the lowest levels seen in decades.
Still, some analysts say the labor market’s underlying strength is weakening. Bloomberg Economics economists Anna Wong, Andrew Husby and Eliza Winger wrote that while the unemployment rate remains stable, job losses are gradually increasing. Although there are still no signs of large-scale layoffs, they said, a labor market marked by both low hiring and low firing is losing momentum.
Separately, October manufacturing data due on Nov. 2 is expected to show solid factory activity. Trade data scheduled for Nov. 4 may indicate a wider deficit as imports related to artificial intelligence increase.
Third-quarter productivity growth, due on Nov. 5, is forecast at 2.6%. If the estimate is met, it would mark the strongest pace of growth in the past year and stand as a key measure of the U.S. economy’s underlying strength alongside labor-market conditions.

Suehyeon Lee
shlee@bloomingbit.ioI'm reporter Suehyeon Lee, your Web3 Moderator.